Visa Gold Debit Digital Card for non-residents of the Republic of Armenia
Buy a payment card, manage your funds, make cash transactions and non-cash payments.
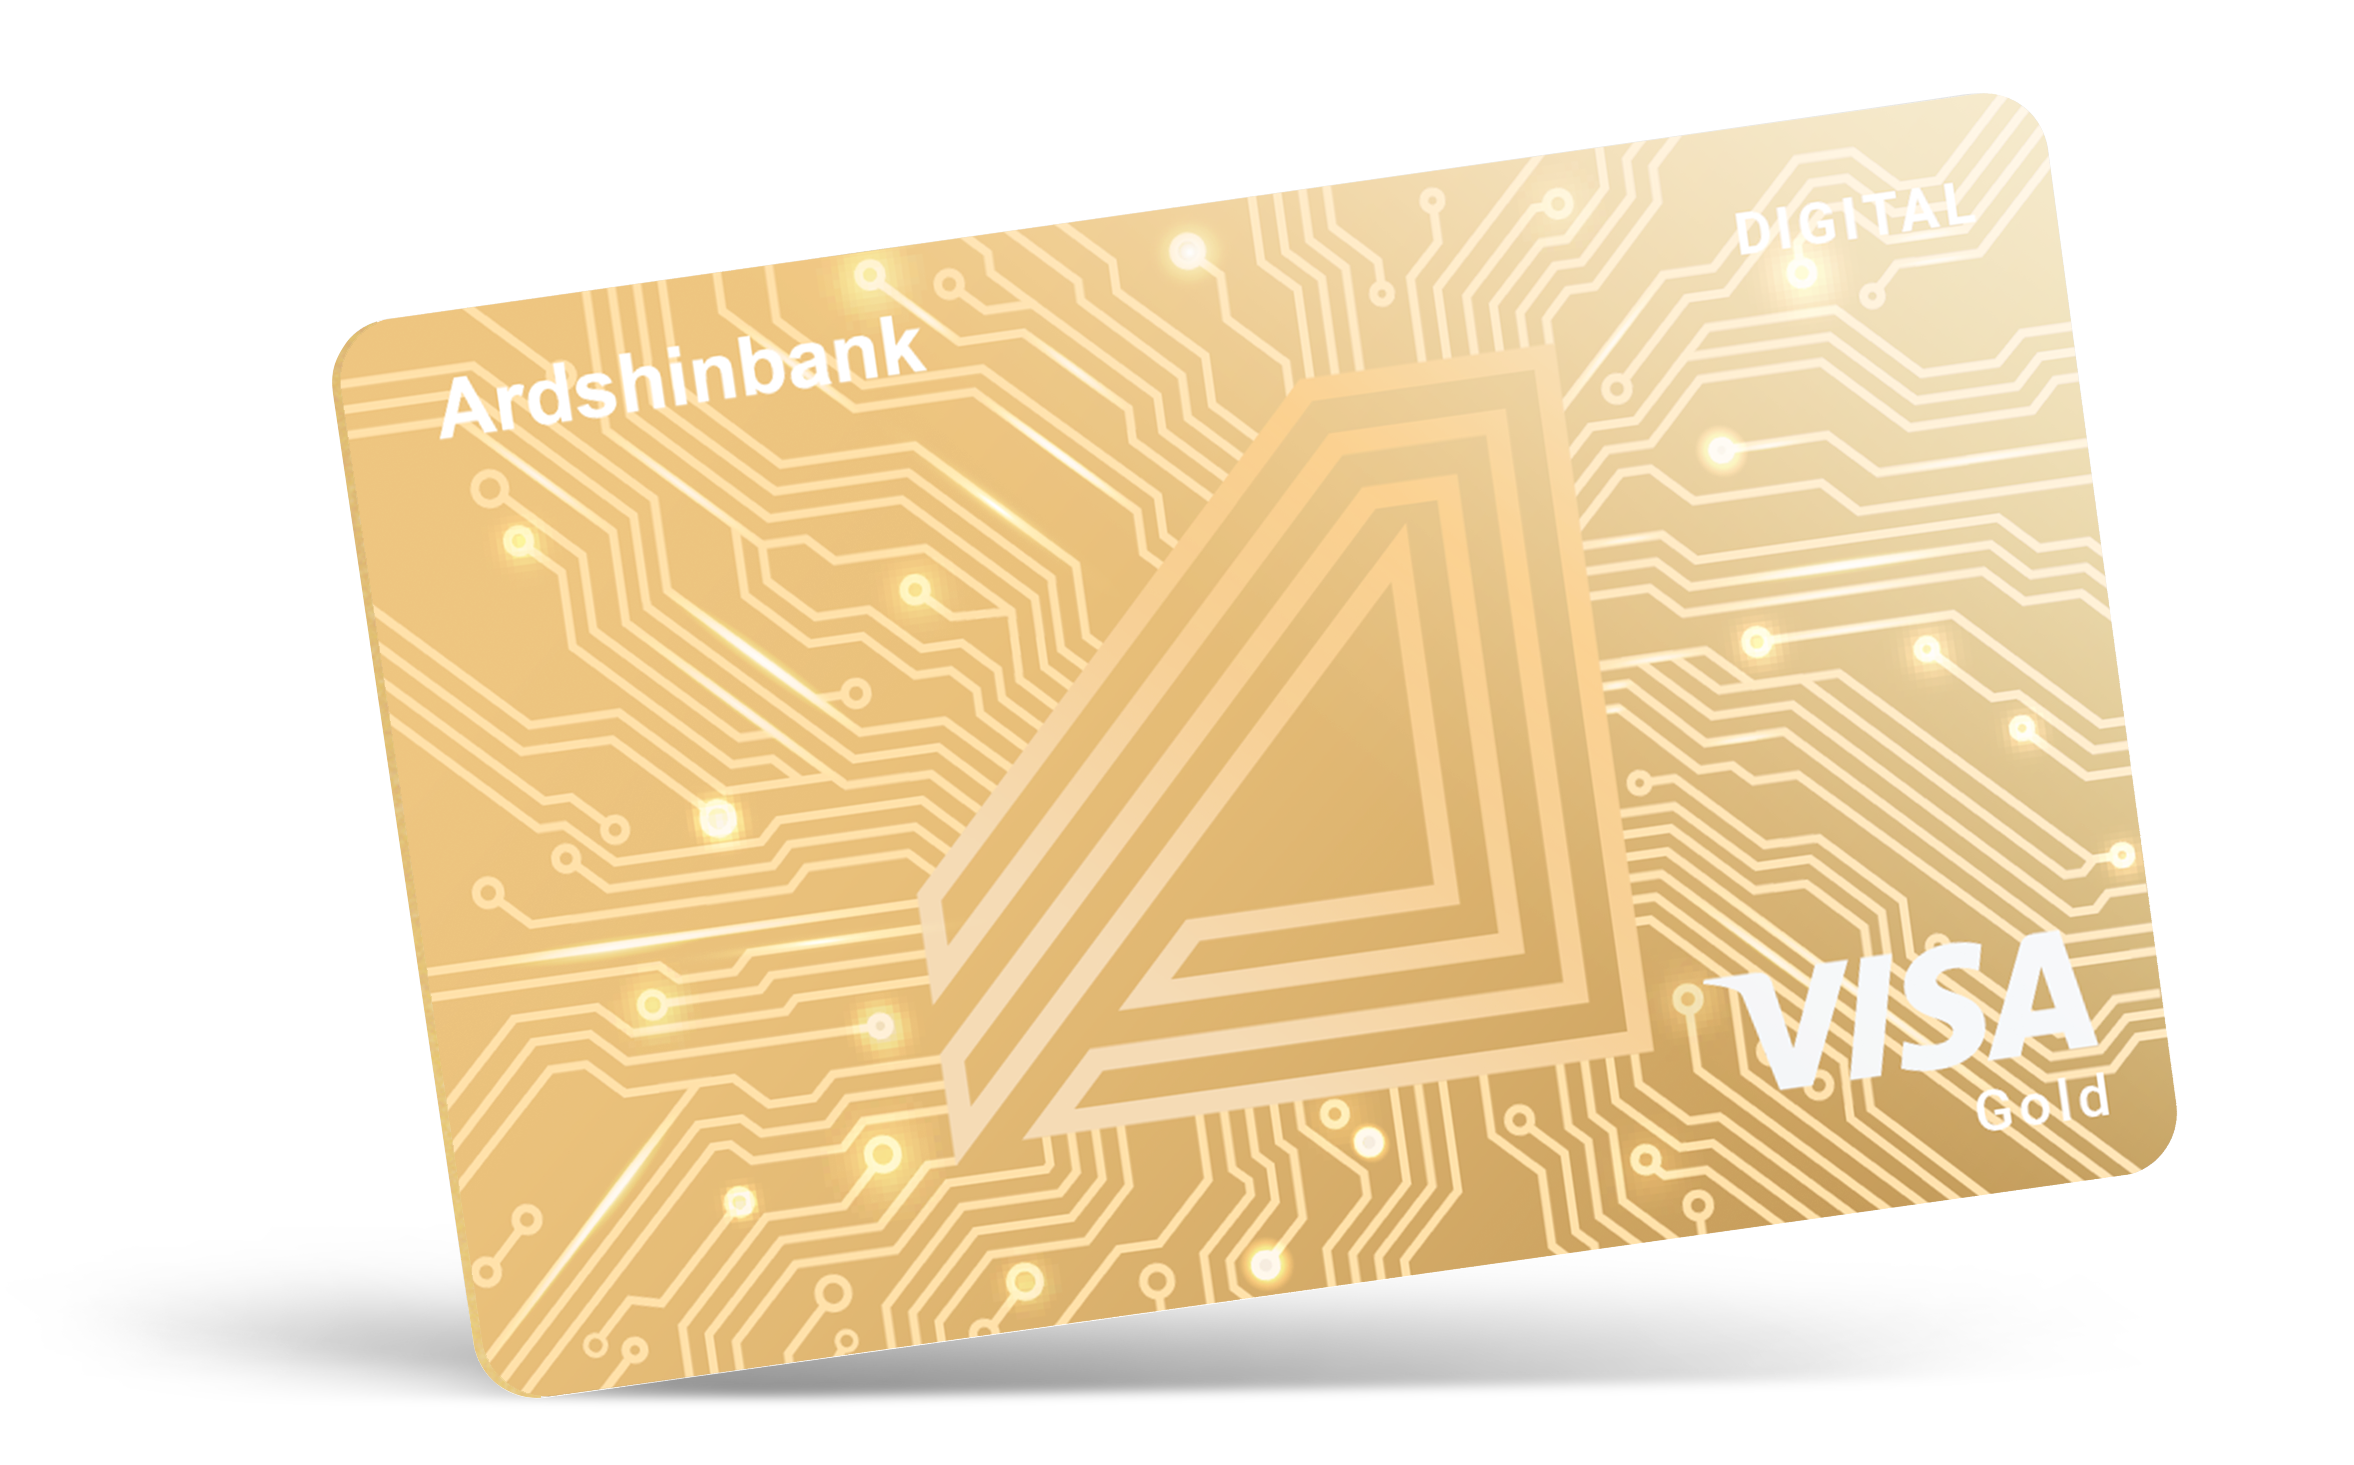
Three steps to order a Digital card
Log in to the Ardshinbank Mobile Banking application
In the Cards section, select the New Card field
Order your digital card in AMD, USD or Euro
|
N |
Visa Gold Debit Digital Card – Non Resident - valid from 25.03.2026 |
AMD |
USD |
EUR |
|
1. General commission fees |
||||
|
1.1 |
Card provision (issue) |
25000 AMD |
25000 AMD |
25000 AMD |
|
1.2 |
Card service fee |
free of charge |
free of charge |
free of charge |
|
1.3 |
Attached card service fee |
card is not provided |
card is not provided |
card is not provided |
|
1.4 |
Cash withdrawal fees***** |
|
|
|
|
1.6.1 |
- via ATMs of the Bank |
0,5% |
0,5% |
0,5% |
|
1.6.2 |
- via cash terminals of the Bank |
1,5% |
1,5% |
1,5% |
|
1.6.3 |
- via ATMs of other banks – members of ARCA system, except for the banks that have connected to the Arca processing center through their own processing: Unibank, Inecobank, AMIO BANK, |
1.5% |
1.5% |
1.5% |
|
1.6.4 |
- via cash terminals of other banks |
2% min 1,500 AMD |
2% min 1,500 AMD |
2% min 1,500 AMD |
|
1.6.5 |
- via ATMs of other banks |
2% min 1,500 AMD |
2% min 1,500 AMD |
2% min 1,500 AMD |
|
|
- via cash-desks of the Bank without presenting the card (also applicable in case of closing the card and the card account) |
According to tariffs of cash transactions of individuals |
||
|
1.5 |
Fee for crediting the card account |
|
|
|
|
|
- up to 200 000 AMD (or equivalent currency) via the Bank’s cash-desk |
0.5% min 100 AMD |
0.5% min 100 AMD |
0.5% min 100 AMD |
|
|
- above 200 000 AMD (or equivalent currency) |
free of charge |
free of charge |
free of charge |
|
|
- Card account replenishment via non-cash transfer |
According to the bank transfers and payments tariffs and terms for individuals |
||
|
|
- Card account replenishment via ATMs of banks serviced by ARCA Processing Center (Cash-in) |
service is unavailable |
||
|
|
- Card account replenishment via ATMs of banks not serviced by ARCA Processing Center (Cash-in) |
service is unavailable |
||
|
1.6 |
Annual simple (nominal) interest rate calculated to the card account balance** |
|
|
|
|
|
- As of the end of day the balance is above or equal to 5,000,000 AMD or 10,000 USD/EUR |
3% |
0,5% |
0,1% |
|
|
- As of the end of day the balance is less 5,000,000 AMD or 10,000 USD/EUR |
0% |
0% |
0% |
|
1.7 |
Fee for non-cash payment for goods and services by cards via payment terminals |
0% |
0% |
0% |
|
1.8 |
- Cash-back |
- |
||
* In case or in the process of insolvency of the Bank's self-service devices (terminals) or inaccessibility of the service for replenishment of accounts and cards at the Bank via those terminals, as well as for the Bank branches (CSD) not furnished with such devices, the tariff is set 0 (zero) AMD.
** Annual simple (nominal) interest rate is the tariff based annual interest rate, according to which the Bank calculates the interest payable to the Client.
Example: 1000 AMD * 5% = 50 AMD for 365 days
The annual percentage yield (APY) is the percentage that a person will receive as a result of a simple interest rate over the 365-day period of 1,000 drams and the interest capitalization and payment frequency.
The annual percentage yield of the deposit is the amount received from the calculation of interest payable at annual interest rate.
The procedure for calculation of annual percentage yield is defined by Regulation 8/02 of the Central Bank of Armenia "On calculation of annual percentage yield of bank deposits".
The Bank shall pay the interest to the Client's account quarterly. According to the RA law "On income tax”, the Bank acts as the tax agent of the depositor through collecting and transferring to the state budget the amount of payable income tax.
*** Documents and/or information with an expired maintenance term in accordance with the legislation of the Republic of Armenia shall not be provided to the Bank's clients.
***** The tariffs are applied at the ATMs and cash terminals upon provision of a PIN code via the Bank’s mobile application.
5 Messages are immediately available on devices connected to the internet; otherwise, the messages can be received after the device is connected to the internet — in the case of Viber, no later than within 24 hours, and in the case of a Push notification, at any time.
In addition to what is specified in these tariffs, additional service commissions may be applied by the servicing bank for cash withdrawal transactions.
1. The fields on the front and back of the card (in particular, the card’s magnetic stripe) contain data about the payment card, which, if accessed by unauthorized persons, may lead to card fraud.
2. The payment card may be damaged due to changes in the temperature of the magnetic strip, the impact of physical force or other reasons. The card cannot be stored near mobile phones, household and office equipment. The Bank reissues the damaged card according to the current tariffs.
3. The cardholder is obligated to ensure the confidentiality of the PIN-code and its inaccessibility to third parties on the basis of the security objectives of the card. The Bank is not liable for the illegal and unauthorized use of the card due to the disclosure (provision) of the PIN by the cardholder to third parties.
4. The PIN-code of the payment card is not used for making transactions on the Internet or other contactless transactions. Therefore, the cardholder does not have to enter his PIN-code when making transactions on the Internet or other contactless transactions.
5. If the cardholder has confidence or doubts that the PIN-code has become available to third parties, it is necessary to immediately apply to the Bank for blocking the payment card and re-generating a new PIN-code via the servicing SST.
6. The SMS notification service allows the cardholder to specify any amount and receive an SMS message in case of authorization of transactions for the given amount or more. Taking into account that payment card operations are in most cases performed after authorization is received, the cardholder is able to effectively and in real time inquire about any authorized operation. The service is especially important for preventing the use of a payment card for fraudulent purposes.
7. When using a payment card in an Internet environment, the cardholder should pay attention to the presence of a "lock" in the corresponding browser field, the Secure Sockets Layer (SSL) or Secure Web Site record indicates that only the cardholder and the merchant can view payment information (details).
Fraud prevention
1. In order to prevent possible fraud by the payment card, the Bank may automatically block payment cards or transactions if the transactions performed by them, according to the Bank's internal criteria, are considered medium or high risk.
2. In case the cardholder confirms that he has performed an operation that serves as the basis for the Bank to suspend the payment card or transactions, the Bank, at the initiative of the cardholder, can unblock this payment card and transactions.