
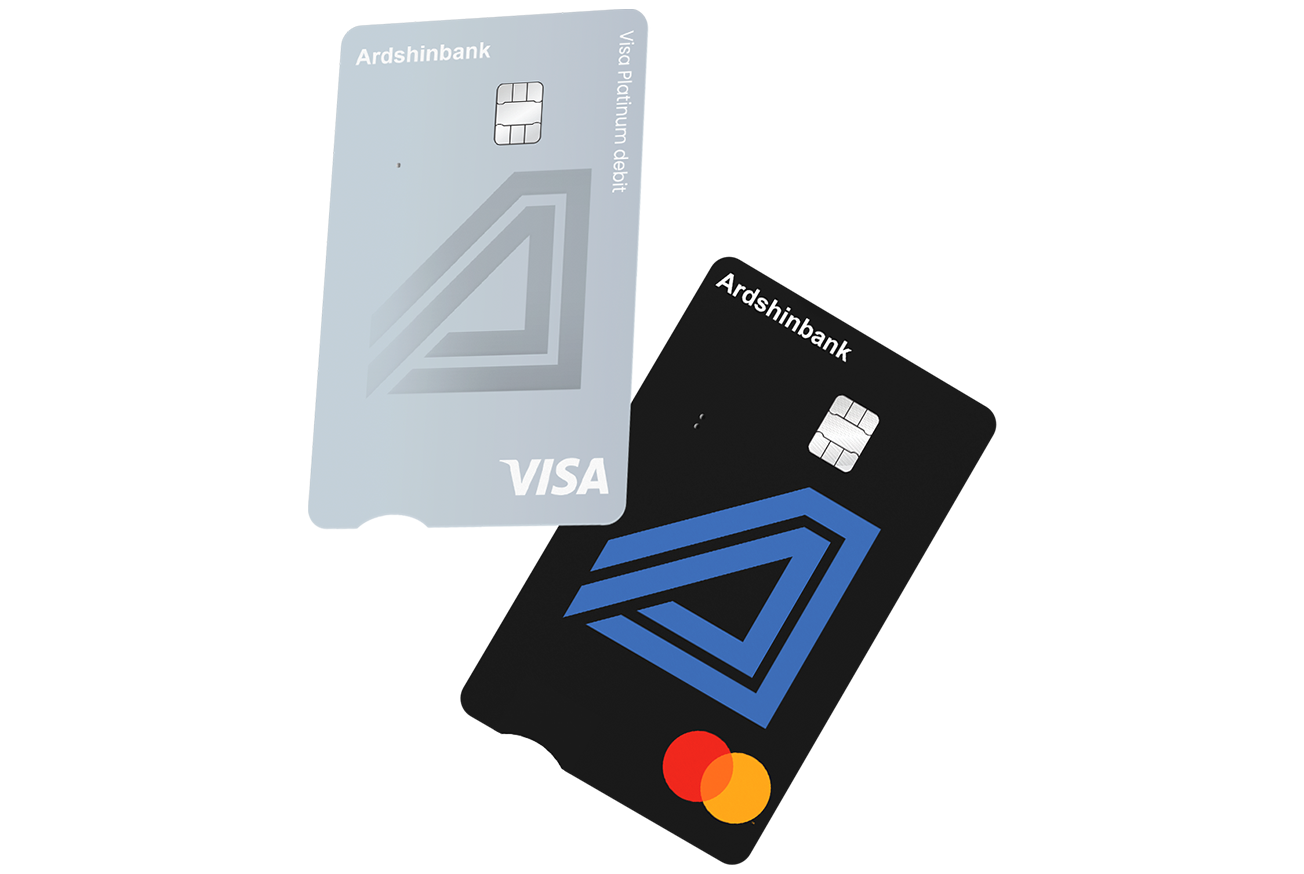
Visa Platinum, Mastercard World
Get a payment card, manage your funds, make cash transactions and cashless payments.
Advantages
- Cashback service in the amount of 1-2% of non-cash payment by card
- Take advantage of the possibility of emergency reissuance of the card abroad.
- Take advantage of the opportunity to provide emergency cash without a card abroad.
- Possibility to get high interest on bank account balance, free SMS notification service.
Access to Visa Concierge service
-2.webp)
- Travel insurance.
- Free use of Business lounge and Fast Track services.
- Free luggage packing.
- Discount offers in the Republic of Armenia and abroad.
- 24/7 information service abroad.
- In case of card loss abroad, emergency reissue or cardless cash up to $5,000.
Main Terms
|
|
Payment card type |
VISA PLATINUM |
MASTERCARD WORLD |
Necessary details |
|
|
Payment card currency |
AMD, USD, EUR |
|
|
|
|
Payment card validity period |
5 years |
|
|
|
|
|
|
||
|
1.1. |
Card provision (issue) |
free |
: An additional fee of AMD 50,000 shall be charged if the Client is identified remotely without physically visiting the Bank for opening an account, issuing or reissuing a card. In case of providing several cards to the Client via remote identification on the same day, one additional fee shall apply. |
|
|
1.2. |
Card service fee if, in the past month, the average daily balance in the account exceeded AMD 200,000 |
free |
In thе particular case, the definition of a month shall apply to the period between concluding the card contract and the day preceding the same date in the next month |
|
|
1.3. |
Card service fee |
AMD 3,000 (if, in the past month, the average daily balance in the account was less than AMD 200,000) |
|
|
|
1.4. |
Card provision (issue) for the use of additiional services |
AMD 7,000 |
The additional services comprise payment card insurance for 1 year with an insurance amount of AMD 200,000. For information about card-attached insurance, click here |
|
|
1.5. |
Attached card monthly service fee |
AMD 2,000 per month |
|
|
|
|
|
|
||
|
2.1
|
With a card, via ATMs of the Bank |
0% for daily transactions worth up to AMD 100,000, as well as estimated equivalent to USD 200 or EUR 200 at the Bank's purchase rate as of the day of registerring the transaction, and 0.5% for transactions exceeding the specified limits, and subsequent transactions |
|
|
|
2.2 |
Via ATMs of the Bank through APPLE PAY / Google PAY |
0.5% |
|
|
|
2.3 |
Withh a Bank, via ATMs of other Banks-members of ArCa |
7.7 |
7.8 |
|
|
2.4 |
With a card via ATMs of other banks - members of ArCa (apart from the banks which connected to the ArCa processing center with their own processing, i.e. – Unibank, Inecobank and AMIO BANK), APPLE PAY / Google PAY transactions |
1.5% |
|
|
|
2.5 |
Via ATMs of other banks |
2% min. AMD 1,500 |
|
|
|
2.6 |
Via the Bank's cash withdrawal units (via POS terminal)5
|
1% |
|
|
|
2.7 |
Via other banks' cash withdrawal units (via POS terminal) |
2% min. AMD 1,500 |
|
|
|
2.8 |
Over-the-counter cash withdrawal at the Bank without a card (applicable also to card and card account closure transactions) |
According to the terms of cash transactions for individuals
|
|
|
|
2.9 |
Fees for Depositing Cash into Card Accounts |
|||
|
2.9.1 |
Depositing cash funds from the Bank’s cash registers |
free |
In case of a failure in operation of self-service machines owned by the Bank, or unavailability of accounts served at the Bank from those machines, and card replenishment service, and throughout that process, as well as for Bank’s branches (CSD) not equipped with self-service machines the tariff shall be AMD 0 (zero). |
|
|
2.9.2 |
Card account replenishment via non-cash transfer |
According to tariffs and terms of bank transfers and payments for individuals |
|
|
|
2.9.3 |
Card account replenishment via ATMs of banks served by ArCa processing system (Cash-in)
|
1.0% |
|
|
|
2.9.4 |
Card account replenishment via ATMs of banks served by ArCa processing system (Cash-in)
|
1․5%
|
|
|
|
2.10 |
Annual simple (nominal) interest rate accrued daily to the card account balance[2] |
The Bank shall pay the payable interest to the Client's account quarterly. According to the RA Law on Income Tax, when paying the accrued interest to the client, the Bank shall act as the tax agent of the depositor through collecting income tax in the amount of interest (income) provided by law and transferring to the state budget.
|
||
|
2.10.1 |
As of the end of the day, the balance equals or is above AMD 5,000,000 or USD 10,000 or EUR 10,000 or CNY 65,000 |
AMD: 3%; USD: 0.5%; EUR: 0.1% |
|
|
|
2.10.2 |
As of the end of the day The balance or is below AMD 5,000,000 or USD 10,000 or EUR 10,000 or CNY 65,000 |
0% |
|
|
|
2.11 |
Commission for non-cash payments with cards for goods and services via payment terminals |
0% |
|
|
[1] The cash-out system functions as follows:
The Client may receive a daily amount of AMD 100,000 without paying a commission fee in the ATMs of the Bank and other banks-members of ArCa. Per one-off transaction exceeding AMD 100,000 or in the event of exceeding the aggregate amount of AMD 100,000, a commission fee shall be charged for the surplus transaction in relation to the transaction amount for the ATM where the transaction was performed. Thus, the client withdrew AMD 70,000 from an ATM integrated into the ArCa payment system, with a subsequent withdrawal on the same day of AMD 50,000 from an ATM of ARDSHINBANK, and then again AMD AMD 30,000 from another Bank’s ATM serviced by ArCa; hence the client will be charged 70,000*0+50,000*0.5%+30,000*1%= AMD 550
[2] « Annual simple (nominal) interest rate is the tariff-based annual interest rate, according to which the Bank shall calculate the interest payable to the Client.
For example: AMD 1000 * 5% = AMD 50 for 365 days
Annual percentage yield (APY) of the account is the percentage that a person shall receive as a result of an annual simple interest rate over the 365-day period for AMD 1,000 deposit and the interest capitalization and payment regular frequency.
Annual percentage yield of the deposit is the amount received from the calculation of 5 interest payable at the interest rate of annual percentage yield. The procedure for calculation of annual percentage yield shall be defined by Regulation 8/02 of the Central Bank of Armenia "On Calculation of Annual Percentage Yield of Bank Deposits."
Additional Terms
|
|
|
|
||
|
3.1
|
Blocking of the card in the Bank's authorization system |
free |
|
|
|
3.2 |
Blocking of the card in the Bank's authorization system |
AMD 15,000 for 2 weeks |
|
|
|
3.3 |
Card re-issue based on the client’s application |
AMD 5,000
|
|
|
|
3.4 |
Unblocking of the card in the Bank’s authorization system for entering an incorrect PIN |
AMD 1,000 |
|
|
|
3.5 |
Payment card and card account closure |
free
|
|
|
|
|
|
|
||
|
4.1 |
Penalty for card account overdraft |
48% per annum |
|
|
|
4.2 |
Closure of inactive cards
|
Inactive cards shall be closed, while the accounts shall continue to operate in accordance with the tariffs and service terms for the bank account.
Within the meaning of this clause, the definition of inactive cards shall apply to cards 6 months past the expiration date and not processed by the client over the past one-year period.
|
|
|
|
|
|
|
||
|
5.1
|
Card-to-card transfer to the Bank’s card |
0.3 % |
|
|
|
5.2 |
Card-to-card transfer to cards of other banks – members of ArCa system |
0.8% |
|
|
|
5.3 |
Card-to-card transfer via VISA Direct / Mastercard MoneySend to cards of other banks – not memebers of ArCa
|
1.5% min․ AMD 800 |
|
|
|
5.4 |
Transfers from the card account |
According to the bank transfers and payments tariffs and terms for individuals (in case of closing the payment card and card account, intra-bank and inter-bank transfers to the RA banks are made free of charge) |
|
|
|
|
|
|
||
|
6.1 |
Payment ring provision |
AMD 125,000 |
With a Platinum card: Only one payment ring shall be provided with one card. When ordering a payment ring for an active card, a card re-issue application shall be submitted. Payment ring shall be provided only with a Visa Classic card |
|
|
6.2 |
Delivery of notifications for authorizations of card transactions, one-time PIN code and secret code for online transactions
|
|
||
|
6.2.1
|
Delivery of SMS for authorizations, one-time PIN code and secret code for online transactions |
free |
The notifications shall be immediately available on devices connected to the internet; otherwise, the notifications can be received after the device is connected to the internet — no later than within 24 hours in the case of Viber or any time - in the case of a Push notification.
To opt for the service of receiving notifications about authorizations, delivery of email notifications shall be activated by default (the service will be available after the launch of a corresponding solution by the Bank). The notification acceptance method may change by the Client - via the Bank's mobile app (the service will be available after the launch of a corresponding solution by the Bank), - by visiting a branch of the Bank or referromg to the personal manager.
|
|
|
6.2.2 |
Delivery of Push notifications for authorizations in Mobile Banking6 |
free |
||
|
6.2.3 |
Delivery of notifications for authorizations via Viber |
free |
||
|
6.2.4 |
Delivery of notifications for authorizations via email |
free |
||
|
6.3 |
Provision of statements and references |
According to tariffs and terms for opening and service of bank accounts for individuals |
Expired documents and/or information in accordance with the legislation of the Republic of Armenia shall not be provided to the Bank's clients. |
|
|
|
|
|
||
|
7.1
|
Daily cash withdrawal limit |
AMD 3,000,000 / USD 6,000 / EUR 5,500 |
|
|
|
7.2 |
Number of daily cash withdrawal transactions |
7
|
|
|
|
7.3 |
Maximum limit of daily non-cash transactions |
AMD 4,000,000 / USD 8,000 / EUR 7,500 |
|
|
|
7.4 |
Number of daily non-cash tramsactions |
30 |
|
|
|
7.5 |
Maximum limit for daily card-to-card transactions to cards issued by ArCa |
AMD 2,500,000 /USD 5,000 /EUR 4,000 |
|
|
|
7.6 |
Number of daily card-to-card transactions to cards issued by ArCa |
5 |
|
|
|
7.7 |
Maximum limit for daily card-to-card transactions to cards not issued by ArCa |
AMD 1,000,000/USD 2,000 /EUR 1,700 |
|
|
|
7.8 |
Number of daily card-to-card transactions to cards not issued by ArCa |
3 |
|
|
|
7.9 |
Maximum limit for weekly card-to-card transactions to cards issued by ArCa |
AMD 9,000,000 /USD 10,000 /EUR 1,000 |
|
|
|
7.10 |
Number of weekly card-to-card transactions to cards issued by ArCa
|
10 |
|
|
|
7.11 |
Maximum limit for weekly card-to-card transactions to cards not issued by ArCa |
AMD 2,500,000 /USD 5,000 /EUR 4,000 |
|
|
|
7.12 |
Number of weekly card-to-card transactions to cards not issued by ArCa |
5 |
|
|
|
7.13 |
Maximum limit for monthly card-to-card transactions to cards issued by ArCa |
AMD 7,500,000/USD 15,000/EUR 14,000 |
|
|
|
7.14 |
Number of monthly card-to-card transactions to cards issued by ArCa |
20 |
|
|
|
7.15 |
Maximum limit of monthly card-to-card transactions to cards not issued by ArCa |
AMD 4,000,000/USD 8,000/EIR 7,000 |
|
|
|
7.16 |
Number of monthly card-to-card transactions to cards not issued by ArCa |
10 |
|
|
|
|
|
8.1 |
The main chip contactless payment card shall be provided to an individual – citizen of RA or another country, aged 14 and older upon provision of proper and valid documents specified in the List of Required Documents for provision of debit (settlement) card. |
|
8.2 |
A payment card shall be provided to RA resident individuals if they have actual residence address in the Republic of Armenia, email address and mobile phone number and to non-resident individuals if they have an email address and a mobile phone number. |
|
8.3 |
A payment card presented in this tariff package may be provided as an attached to a card holder having international classic or premium debit (settlement) card of the Bank and submitting proper and valid documents specified in the List of Required Documents for provision of debit (settlement) card. Any individual, irrespective of citizenship and age, including holder of the main card, may be a holder of an attached card. |
[1] The cash-out system functions as follows:
The Client may receive a daily amount of AMD 100,000 without paying a commission fee in the ATMs of the Bank and other banks-members of ArCa. Per one-off transaction exceeding AMD 100,000 or in the event of exceeding the aggregate amount of AMD 100,000, a commission fee shall be charged for the surplus transaction in relation to the transaction amount for the ATM where the transaction was performed. Thus, the client withdrew AMD 70,000 from an ATM integrated into the ArCa payment system, with a subsequent withdrawal on the same day of AMD 50,000 from an ATM of ARDSHINBANK, and then again AMD AMD 30,000 from another Bank’s ATM serviced by ArCa; hence the client will be charged 70,000*0+50,000*0.5%+30,000*1%= AMD 550
[2] « Annual simple (nominal) interest rate is the tariff-based annual interest rate, according to which the Bank shall calculate the interest payable to the Client.
For example: AMD 1000 * 5% = AMD 50 for 365 days
Annual percentage yield (APY) of the account is the percentage that a person shall receive as a result of an annual simple interest rate over the 365-day period for AMD 1,000 deposit and the interest capitalization and payment regular frequency.
Annual percentage yield of the deposit is the amount received from the calculation of 5 interest payable at the interest rate of annual percentage yield. The procedure for calculation of annual percentage yield shall be defined by Regulation 8/02 of the Central Bank of Armenia "On Calculation of Annual Percentage Yield of Bank Deposits."
In case of any difference between the payment cards tariffs in banking services packages and these tariffs, the tariffs in the packages shall prevail.
You can learn about the benefits associated with the MC World by following the link here
For information about the benefits of the VS Platinum card, click the link here
The Bank's MOBILE BANKING app enables transactions such as money transfers, loan repayments, overview of account balances and transactions, payments and various transactions available here.
Apart ftom the terms specified in these tariffs, additional service commissions may be imposed by the servicing bank for the conduct of the transaction.
1. The fields on the front and back of the card (in particular, the card’s magnetic stripe) contain data about the payment card, which, if accessed by unauthorized persons, may lead to card fraud.
2. The payment card may be damaged due to changes in the temperature of the magnetic strip, the impact of physical force or other reasons. The card cannot be stored near mobile phones, household and office equipment. The Bank reissues the damaged card according to the current tariffs.
3. The cardholder is obligated to ensure the confidentiality of the PIN-code and its inaccessibility to third parties on the basis of the security objectives of the card. The Bank is not liable for the illegal and unauthorized use of the card due to the disclosure (provision) of the PIN by the cardholder to third parties.
4. The PIN-code of the payment card is not used for making transactions on the Internet or other contactless transactions. Therefore, the cardholder does not have to enter his PIN-code when making transactions on the Internet or other contactless transactions.
5. If the cardholder has confidence or doubts that the PIN-code has become available to third parties, it is necessary to immediately apply to the Bank for blocking the payment card and re-generating a new PIN-code via the servicing SST.
6. The SMS notification service allows the cardholder to specify any amount and receive an SMS message in case of authorization of transactions for the given amount or more. Taking into account that payment card operations are in most cases performed after authorization is received, the cardholder is able to effectively and in real time inquire about any authorized operation. The service is especially important for preventing the use of a payment card for fraudulent purposes.
7. When using a payment card in an Internet environment, the cardholder should pay attention to the presence of a "lock" in the corresponding browser field, the Secure Sockets Layer (SSL) or Secure Web Site record indicates that only the cardholder and the merchant can view payment information (details).
Fraud prevention
1. In order to prevent possible fraud by the payment card, the Bank may automatically block payment cards or transactions if the transactions performed by them, according to the Bank's internal criteria, are considered medium or high risk.
2. In case the cardholder confirms that he has performed an operation that serves as the basis for the Bank to suspend the payment card or transactions, the Bank, at the initiative of the cardholder, can unblock this payment card and transactions.